Key Takeaway:
The fintech app development cost typically depends on the product’s scope, integrations, security, compliance, and scale:
- Basic fintech MVP: $30,000 – $80,000 for validating one core financial workflow with essential features.
- Market-ready fintech app: $80,000 – $150,000 for live financial integrations, production-grade security, and compliance requirements.
- Enterprise fintech platform: $150,000-$300,000+ for multi-market operations, advanced automation, AI capabilities, and enterprise-grade infrastructure.
Beyond the initial build, fintech products also require ongoing costs for cloud infrastructure, third-party APIs, compliance, security, maintenance, and usage-based services throughout the product lifecycle.
Table of Contents
Introduction
You get 3 fintech app development quotes and somehow end up with completely different numbers.
One estimates you at $20,000, another puts the project at $150,000, while a third exceeds $500,000. The gap is huge, but the bigger question is: what does each estimate actually cover?
Fintech products carry different technical, security, integration, and regulatory requirements, and many estimates leave out the costs that appear outside the development contract.
Is the quote for an MVP or a production-ready platform? Does it include financial integrations, compliance, licensing, banking infrastructure, and post-launch support?
This blog breaks down fintech app development costs in 2026 by the factors that influence the budget, along with the one-time and recurring expenses that can shape your first-year investment.
What Are the Types of Fintech Apps and How Much Does Each Cost to Build?
Fintech offers a wide range of products, and each one solves a different problem. Here’s a breakdown of the major fintech app types, what goes into building each one, and how the fintech app development cost for each is driven by scope and complexity.
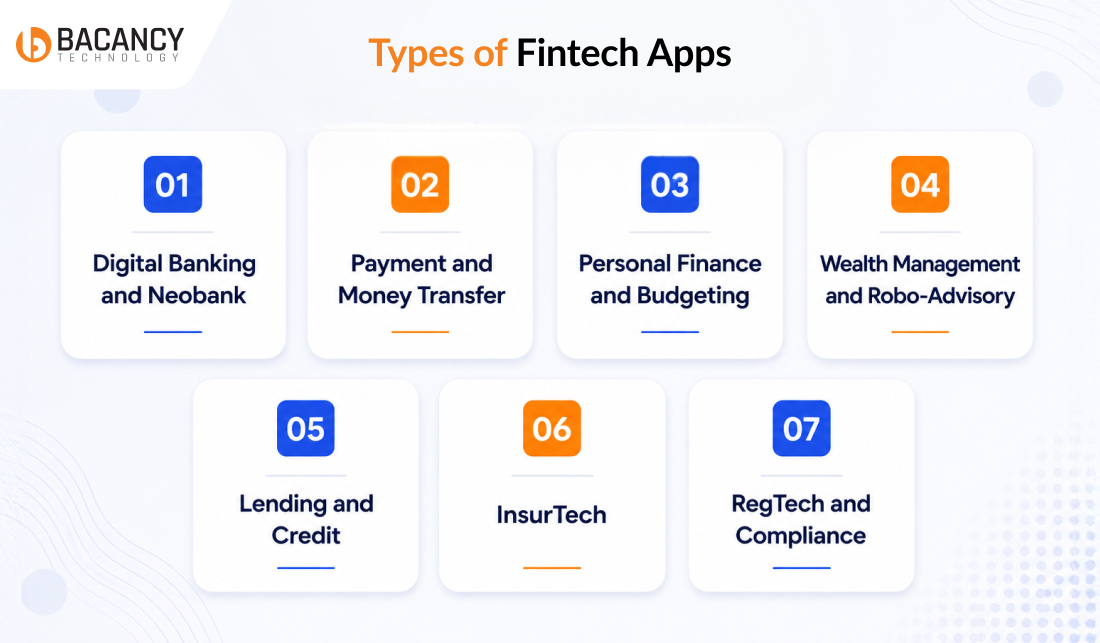
1. Digital Banking and Neobank Apps
A neobank is a bank with no branches. In digital banking and neobanking, everything a customer requires, such as opening an account, checking balances, moving money, or freezing a card, happens online. These financial applications are backed by a licensed banking partner and follow compliance guidelines.
Despite that, several neobanks layer in saving goals, spending insights, or early paycheck access to compete with traditional banks on convenience rather than branch count.
The cost to develop fintech app is based on KYC/AML integration, core banking connections, multi-currency support, card issuance partnerships, and real-time transaction processing.
2. Payment and Money Transfer Apps
A payment app moves money from one place to another quickly. That might be a person splitting dinner with a friend, a business accepting a card tap, or a worker sending part of their paycheck home to another country.
The interface is simple. What sits underneath is not. The app has to talk to banks, card networks, and currency systems to settle every transaction correctly.
Your fintech app development cost depends on payment gateway integrations, fraud detection, PCI DSS compliance, multi-currency conversion, and settlement logic.
3. Personal Finance and Budgeting Apps
A personal finance app connects you to the user’s bank accounts and cards, which pulls in every transaction and converts that raw data into something readable. It shows where the money went, how much is left, and whether spending is trending up or down.
Budgeting apps help your users to create monthly budgets, set spending limits, allocate money across different categories, and plan for savings goals. You can see how much users have spent on essentials, subscriptions, dining, or entertainment without exceeding their budgets.
Cost is based on open banking API integrations (Plaid, Yodlee, or regional equivalents), data categorization logic, and secure account aggregation.
4. Wealth Management and Robo-Advisory Apps
Wealth management or robo-advisory applications help your users to manage investments without requiring constant interaction with a financial advisor. The user enters their financial goals, investment horizon, risk tolerance, and the app recommends a suitable portfolio.
The more advanced platforms are you can automatically rebalance investments as market conditions change or the user’s goals change.
Fintech app development cost scales with portfolio management and rebalancing algorithms, brokerage API integrations, real-time market data feeds, investment dashboards, and regulatory compliance such as SEC and FINRA requirements or their equivalents in other markets.
5. Lending and Credit Apps
A lending app takes a borrower from application to funded loan without a loan officer to manage every step manually. It collects your personal and financial information, verifies the app’s identity, checks credit history, evaluates repayment capacity, and determines whether the app meets the lender’s criteria.
Once approved, the app can manage loan disbursement, repayment schedules, notifications, and account servicing. BNPL, personal loans, business loans, and other digital lending products follow this same basic workflow, although each can use different eligibility rules, risk models, loan terms, and repayment structures.
Cost to develop fintech app is based on credit bureau integrations, KYC and identity verification, underwriting engines, credit scoring models, loan origination workflows, payment integrations, and loan servicing features.
6. InsurTech Apps
An InsurTech app brings insurance activities, such as policy selection, premium payments, claims filing, document access, and coverage tracking, into a self-service digital platform. The advanced platform features include real-time data that personalizes premiums and coverages.
For instance, a usage-based auto insurance app can collect driving data through connected devices and adjust premiums based on driving behavior rather than relying only on traditional risk factors.
The fintech app development cost here reflects policy administration system integration, claims automation, underwriting workflows, payment processing, customer portals, and third-party data integrations covering vehicle, property, health, or IoT data.
7. RegTech and Compliance Apps
A RegTech app is designed for the teams responsible for financial compliance rather than everyday customers. It monitors transactions, customer activity, and financial data to identify suspicious behavior, potential compliance violations, or activities that require further investigation.
The complexity increases when the app must support multiple markets or regulatory frameworks. Instead of rebuilding the platform whenever regulations change, a well-designed RegTech system uses configurable rule engines that allow compliance teams to update rules, thresholds, and workflows without major changes to the core application.
Cost is based on regulatory rule engines, transaction monitoring, data integrations, automated reporting, case management, audit trails, and the number of regulatory frameworks the platform needs to support.
Want to develop a fintech app for your niche market?
Hire fintech developers from Bacancy Technology to build secure, scalable solutions tailored to your product, financial workflows, and market needs.
How Much Does It Cost to Develop Fintech App in 2026?
The table below gives working ranges by product type. MVP cost covers a first release that can operate in one market. Full-scale cost covers a production platform with complete feature depth, multi-market support, and mature security and compliance.
| Fintech Product | MVP Cost | Full-Scale Cost |
|---|
| Digital Banking & Neobank | $80,000 to $300,000 | $500,000+ |
| Payment & Money Transfer App | $40,000 to $150,000 | $150,000 to $400,000 |
| Personal Finance & Budgeting App | $30,000 to $100,000 | $120,000 to $200,000 |
| Wealth Management & Robo-Advisory App | $100,000 to $200,000 | $200,000 to $350,000 |
| Lending & Credit App | $60,000 to $250,000 | $250,000 to $500,000+ |
| InsurTech App | $70,000 to $150,000 | $150,000 to $300,000 |
| RegTech & Compliance App | $100,000 to $200,000 | $200,000 to $300,000 |
What Factors Influence Fintech App Development Costs?
The primary factors that impact fintech app development costs are team expertise, development approach, and project scope. The MVP build will cost less than full-feature apps, cross-platform development costs less than native, and the level of QA and security testing required also changes the total price.
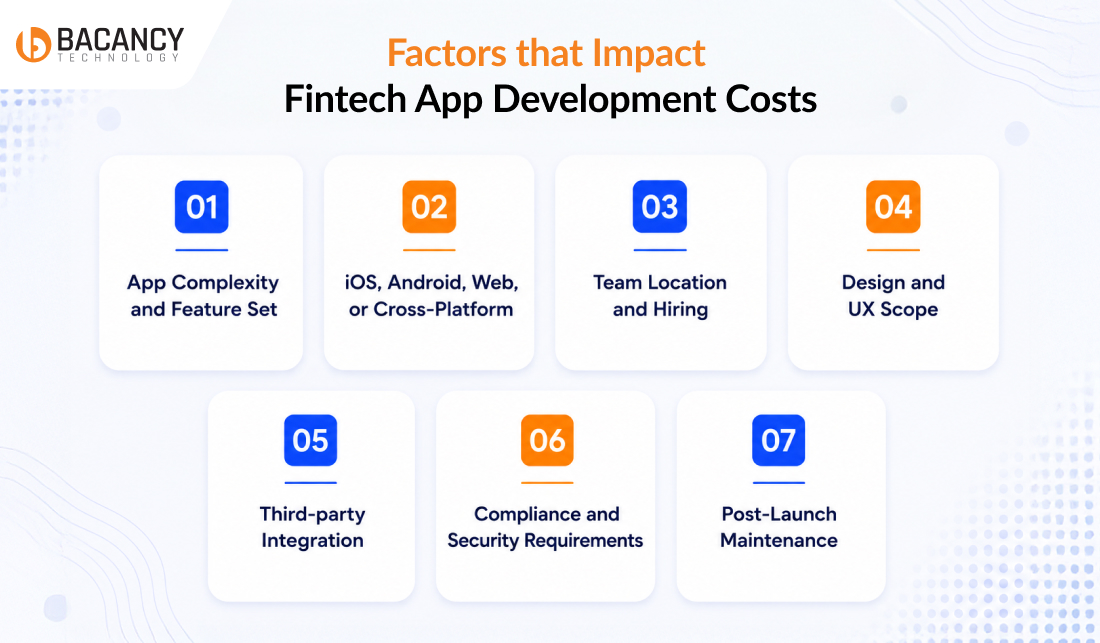
1. App Complexity and Feature Set
Start with what you want the application to add. A personal finance app with expense tracking and budgeting has a simpler scope than a digital banking app with account opening, card management, payments, transfers, and real-time transactions.
Advanced features add further complexity. Automated underwriting, investment management, fraud detection, AI recommendations, and multi-currency support require additional backend logic, integrations, and testing.
If you are launching an MVP, you must separate essential features from those you can introduce later. It keeps the initial development focused.
The platform you choose affects your fintech app development cost. A native app for iOS and Android requires separate development for each platform. A cross-platform approach lets you reuse much of the code.
You may also need a web-based admin panel. Your internal teams can use it for KYC reviews, transaction monitoring, account management, and reports.
Each additional platform adds development and testing work. It also increases future maintenance costs. Decide which platforms your customers and internal teams need before development begins.
3. Team Location and Hiring Model
Your choice of development team can change the project budget considerably. An in-house team comes with recruitment, salaries, benefits, infrastructure, and management costs
Outsourced and offshore teams usually follow a different pricing structure. It can also give you access to developers with specific fintech experience.
That experience matters when your app involves payment systems, banking APIs, KYC, security, or financial data. A team with relevant experience can handle these requirements with fewer delays and less rework.
When you compare quotes, look beyond the hourly rate. Check the team’s fintech experience, project scope, timeline, and the work included in the final price.
4. Design and UX Scope
Fintech apps involve several financial journeys. Users may need to complete KYC, open an account, make payments, transfer money, check investments, or apply for a loan.
Each journey needs a clear and simple interface. A basic finance app may need a smaller design scope. A banking or investment platform may require detailed dashboards, financial charts, verification screens, and multiple user flows.
Custom UX research, prototypes, usability tests, accessibility, and design systems can add to the cost to develop fintech app. More complex financial workflows also require more design work.
5. Third-Party Integrations
Most fintech apps depend on external financial services. These may include payment gateways, banking APIs, open banking providers, KYC/AML services, credit bureaus, card networks, and fraud detection platforms.
Each integration requires development and testing. Developers also need to handle authentication, data mapping, error management, and communication between systems.
Complex banking and payment integrations may require more work. This can include transaction synchronization, reconciliation, webhooks, and monitoring.
Also consider the provider’s own fees. Some services charge per transaction, verification, API request, or active user. These become ongoing costs after launch.
6. Compliance and Security Requirements
Compliance requirements depend on your fintech product and target market. A budgeting app may have different requirements from a payment platform or digital bank.
Depending on your business model, you may need KYC, AML, PCI DSS, GDPR, SOC 2, encryption, access controls, audit trails, fraud monitoring, or penetration testing.
These requirements affect the technology behind the app. They can influence the architecture, infrastructure, authentication, data storage, development, and testing.
Multiple countries can add further requirements. Each market may have its own financial regulations and security standards. Working with a fintech consulting company to define these requirements early gets you a more accurate development estimate.
7. Post-Launch Maintenance
The development cost does not end when the app goes live. Financial apps depend on APIs, cloud infrastructure, operating systems, security tools, and regulatory requirements.
These components can change over time. Your app may need security updates, API changes, bug fixes, infrastructure upgrades, performance checks, or compliance updates.
Your user base and transaction volume may also grow. This can create a need for additional infrastructure and performance improvements.
The maintenance requirement depends on the type of fintech app. Payment and banking platforms usually need more continuous support than simpler financial management apps.
Which Fintech Costs are One-Time, Recurring, and Usage-Based?
The cost to develop a fintech app is more than the development quote. Some expenses occur once, some will continue every year, and others increase with every transaction or verification. With the separate costs, you can get a clear picture of what you will spend as the product grows or changes.
One-Time Costs
These are the expenses you usually pay during the initial build:
- Development: Designing, building, testing, and launching the app within the agreed scope.
- UI/UX Design: User research, flows, wireframes, visual design, design systems, and component libraries.
- Initial Integrations: Engineering work to connect banking APIs, payment gateways, KYC providers, and other third-party services.
- Initial Security Implementation: Security architecture, encryption, key management, access controls, and initial hardening.
Recurring Costs
These expenses continue after the app goes live, even when you do not add major new features.
- Maintenance: Bug fixes, dependency updates, platform updates, and technical improvements.
- Cloud Infrastructure: Baseline compute, storage, databases, backups, and hosting resources.
- Monitoring and Observability: Log, metric, trace, alerting, and transaction-monitoring systems.
- Ongoing Security and Compliance: Security tools, vulnerability management, periodic penetration tests, security reviews, and compliance audits.
- Support and Operations: Customer-support platforms, technical support, and operational staff.
Usage-Based Costs
These expenses depend directly on how much your customers use the product.
- KYC and Identity Verification: Fees based on verification attempts, applicants, documents, biometric checks, or manual reviews.
- AML and Fraud Screening: Charges for sanctions, watchlist, PEP, fraud, and ongoing customer monitoring.
- Payment Processing: Percentage-based, fixed per-transaction, cross-border, refund, dispute, or chargeback fees.
- Third-party API and Platform Fees: Charges based on API calls, connected accounts, active users, or provider transactions.
- Financial Data: Per-request, per-user, per-account, or subscription fees for credit, market, transaction, and account data.
With these costs in mind, you can compare application development services based on the complete cost of building and running your fintech product.
How Much Should You Invest in a Fintech MVP?
A fintech MVP should prove that the core financial workflow works and that customers are willing to use it. You do not need every feature in the first release. You need enough functionality to test the product in a market.
Core Transaction or Product Workflow
Estimated Investment: $30,000 – $80,000
This fintech app development cost tier covers the basic workflow behind the product: user registration, profiles, the primary transaction or financial function, a basic dashboard, notifications, and essential backend services.
For instance, a budgeting app may focus on account connection, transaction tracking, and budget creation. A payment app will highlight user onboarding, payment initiation, transaction history, and basic notifications.
This works when you want to validate the concept before a larger investment.
Market-Ready MVP
Estimated Investment: $80,000 – $150,000
A market-ready MVP works beyond the core workflow. It adds essential third-party integrations, powerful security, and production infrastructure.
It depends on the product; it may include payment gateways, banking APIs, fraud detection, role-based access, admin tools, analytics, and production-grade monitoring.
Scalable Product
Estimated Investment: $150,000-$300,000+
A scalable product includes the foundation required for larger users and transaction volumes. It might add workflow automation, advanced analytics, AI capabilities, stronger security controls, multi-region infrastructure, and upgraded financial features.
How Much Does AI Add to Fintech App Development Costs in 2026?
AI in fintech app development costs will be around $20,000 to $150,000+. It depends on the addition of AI integration into your fintech applications.
A simple AI feature such as transaction categorization or financial assistance may require a relatively small additional investment.
For instance, an AI system for fraud detection requires historical transaction data, model development, real-time inference, monitoring, and continuous model evaluation. An AI lending system needs credit risk models, decision rules, explainability, and additional compliance controls.
The cost to develop fintech app also depends on whether you use an existing AI model through an API or build and train a custom model. API-based solutions usually have a lower initial development cost, while custom models require more data engineering, infrastructure, testing, and maintenance.
If AI is part of your fintech product, estimate the cost of the AI feature and its ongoing usage separately from the core application. API calls, model inference, data storage, model monitoring, and periodic updates can become recurring expenses.
Have an AI use case in mind for your fintech app?
Our fintech app development services help you turn it into production-ready features built for security, scale, and real-world financial workflows.
How to Estimate the Budget for a Fintech App Project?
Start with the product scope rather than a single development rate. List the features required for the MVP, the platforms you need, and the financial systems your app must connect with.
Then estimate the major cost areas:
Development + UI/UX + integrations + security and compliance + infrastructure + testing + post-launch support = estimated project budget
Next, separate the costs that occur once from those that continue after launch. Development and initial design are usually one-time expenses. Cloud infrastructure, maintenance, security, third-party services, KYC checks, payment processing, and API usage can continue throughout the product’s life.
Your target market also matters. A fintech app for one country may have a simpler regulatory scope than a platform that operates across several markets. The same applies to transaction volume. A product that processes thousands of transactions per month will have very different operating costs from one that processes millions.
For a more realistic estimate, define these 5 areas before requesting quotes:
1. What the MVP must do
2. Which platforms you need
3. Which financial and third-party systems you need to connect
4. Which security and regulatory requirements apply
5. How many users and transactions you expect after launch
Once these are clear, development teams can provide a scope-based estimate instead of a broad number that may change significantly later.
Conclusion
A successful fintech product needs more than a polished interface. Every payment, account verification, banking integration, security, and compliance adds to the work behind the product.
So, before you finalize your fintech app development cost, look at the complete picture. You need to consider the MVP scope, third-party integrations, security requirements, infrastructure, and the costs you continue to manage after launch.
As a trusted fintech IT solutions and services partner helps you make these decisions early and avoid unexpected development and operational expenses later. Bacancy Technology offers 14+ years of experience and 100+ finance projects to assist your businesses build fintech solutions that are secure, growth-ready, and adaptive to what comes next.
Frequently Asked Questions (FAQs)
In most cases, yes, by operating under a sponsor bank or a banking-as-a-service provider whose license includes your activity. You need to trade upfront capital for your ongoing revenue share and control.
The cost to develop a fintech app is higher because it requires an advanced user experience and interface. Fintech apps will require secure payment processing, financial API integration, encryption, identity verification, fraud detection, regulatory compliance, audit trails, and reliable transaction infrastructure. These backend systems also add more development, testing, security, and compliance work than a standard app.
It takes 1 to 3 months after the fintech app development finishes. It starts earning revenue as soon as it launches with a monetization model and acquires paying users; however, the actual timeline varies by business model. Payment apps may generate revenue from transaction fees, while investment and lending apps may take longer than others.
The most common causes of fintech budget overruns are scope changes, complex financial integrations, security and compliance requirements, third-party API costs, and underestimated backend work. Budget issues also arise when teams discover legacy-system limitations, add new features during development, or delay decisions about KYC, AML, PCI DSS, data protection, and transaction workflows.
Yes, launching a fintech app in one market first can reduce initial fintech app development cost and risk. It is especially considerable when the product has different regulatory, payment, tax, or KYC requirements across countries.