Quick Summary
This blog covers the top agentic AI use cases in finance, including fraud detection, reconciliation, KYC, forecasting, and collections. It explains how to choose the right use case, assess risks, and test your first pilot. You’ll also learn how AI agents in finance can automate tasks, improve workflows, and scale safely.
Table of Contents
What Is Agentic AI in Finance?
Agentic AI in finance refers to AI systems that can plan tasks, make decisions, take actions, and adjust their next steps to reach a goal. A finance team sets the goal and rules, while the agent handles the steps in between.
For example, an accounts receivable agent can review overdue invoices, decide which of your customers need a reminder or call, draft an outreach, update the CRM, and also flag high-risk accounts for finance professionals to review.
Agentic AI could add $3 trillion in productivity gains worldwide. Yet, it differs from traditional AI because it can make decisions, take actions, and change its next steps based on what it finds.
- Agentic AI versus RPA: RPA has static instructions and works well for repetitive tasks. Agentic AI, on the other hand, can manage changing circumstances and make decisions about the next steps based on the data gathered by itself.
- Agentic AI versus chatbots: A chatbot reacts to the user’s request step-by-step. An agentic AI system can complete an entire multistep process independently and seek help from a human if necessary.
- Agentic AI versus Generative AI: The output of generative AI is generated content, for example, summaries, reports, or draft text. While, agentic AI can use the result of generative AI to take further action.
This makes agentic AI in finance a strong fit for tasks that include numerous steps, constantly changing information, and decisions instead of simple rule-based automation.
The Scoring Framework: 5 Criteria That Actually Predict Pilot Success
Not every finance workflow is the right fit for Agentic AI. Before you start working on the pilot, you must score all of your agentic AI use cases in finance against five practical factors. This helps you avoid complex projects with unclear returns and focus on AI agents in finance that can deliver the best results.
1. Is the data ready to use today?
You must check if the agent has the right access to clean and correct data from the systems. If the key information is incomplete, outdated, or locked in different systems, the pilot will slow down.
2. Does the workflow follow clear decision rules?
When a workflow follows clear patterns like matching transactions, reviewing any documents, or verifying compliance data, agentic AI works best. The more consistent the process, the easier it is to automate safely.
3. What happens if the agent gets it wrong?
Always consider the financial and regulatory impact if an action goes wrong. AI agents in finance can handle low-risk tasks on their own, while decisions such as credit approvals and compliance checks should require human oversight
4. How many systems does it need to connect to?
An agent might need data from core banking systems, payment platforms, CRM tools, spreadsheets, or compliance databases. Fewer integrations mean a faster and less complicated pilot.
5. How fast can you see the results?
Prioritize agentic AI in finance use cases where the results can be measured within a specific time frame. Look for clear metrics such as reduced investigation time, fewer manual hours, faster reconciliation, or lower false positives.
How To Choose the Right Agentic AI Use Cases in Finance for Your Institution
The starting point for agentic AI in finance depends on where your finance team loses most of their time, where manual decisions are still being taken, and where an AI agent can work within clear rules. You can use these four situations to identify the best fit.
1. If You Have High Volume and Strong Fraud Rules
You can begin with fraud detection and investigation. Agentic AI can review a large number of transactions, connect signals across accounts, pinpoint any suspicious cases, gather supporting data, and send high-risk cases to investigators. This is a strong starting point when your existing fraud rules generate more alerts than your team can review quickly.
2. If Manual Month-End Close Is the Problem
Start with financial close and reconciliation. An agent can help you compare transactions across systems, match records, identify breaks, collect data, and prepare exceptions for the finance team. This helps you reduce manual checks that slow down the close without giving the agent final control over the financial decisions.
3. If You Have Not Built Anything Yet
You can start with one narrow repeatable workflow, not a broad AI program. Choose a task that has clear inputs, measurable output, and limited risk, such as invoice follow-ups, reconciliation exceptions, or document checks. Prove the workflow works before connecting the agent with more systems or giving it more authority.
4. If You Already Ran One Pilot
Do not start working on another disconnected pilot. Turn the working pilot into a production workflow for agentic AI in finance. Review where the agent still needs a manual approval, measure accuracy and the time that you have saved, strengthen access controls, and connect it with the systems it needs. The goal is to move from an AI demo to a reliable AI agent.
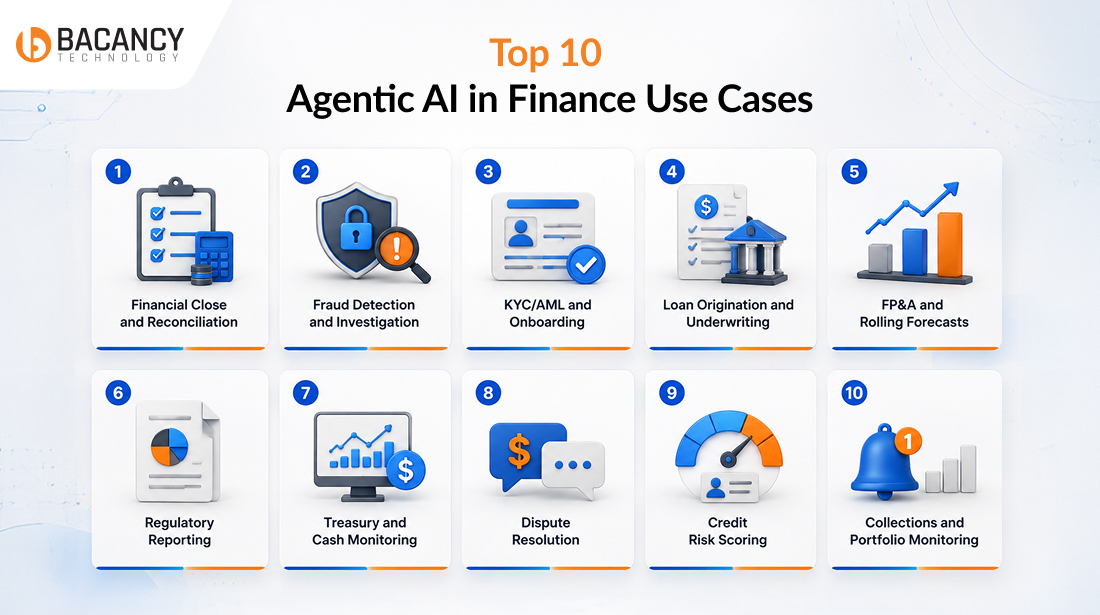
Top 10 Agentic AI in Finance Use Cases
Let’s quickly review the 10 best agentic AI in finance use cases below and see how AI agents in finance can handle tasks, analyze data, and take the right actions to support your business.
1. Financial Close and Reconciliation
Month-end close usually means pulling data from multiple systems, matching transactions, finding any discrepancies, and preparing accounts for a review. With agentic AI in finance, even small exceptions can require finance teams to move between ledgers, bank records, and spreadsheets. This makes the process slow and leaves less time for actual analysis.
What an agentic AI system does differently:
- Pulls data from connected financial systems and automatically matches transactions
- Finds any discrepancies and investigates related reports to identify possible causes
- Makes groups of similar exceptions so teams can resolve issues faster
- Reroutes unresolved issues to the right finance team with supporting evidence
- Tracks open reconciliation items until they are resolved
2. Fraud Detection and Investigation
Fraud does not usually appear as one suspicious transaction. It can involve small transfers, new beneficiaries, unusual login activity, and rapid movement of funds across connected accounts. Traditional systems often review these signals separately, making it harder to spot larger fraud patterns.
What does an Agentic AI system do differently:
- Builds behavioral profiles that can identify activity that differs from a customer’s normal pattern
- Connects transactions across accounts, beneficiaries, devices, locations, and payment channels
- Combines various weak signals into a single risk pattern
- Prioritizes cases based on risks and shows investigators the signals behind every alert made
- Picks up transaction history and supporting data for investigation automatically
3. KYC/AML and Onboarding
KYC and AML teams need to collect customer information, verify documents, run screenings, and investigate alerts across various systems. Any missing information or potential matches can create longer review cycles. Also, as the customer volume increases, manual checking becomes harder to maintain consistently.
What does an Agentic AI system do differently:
- Reviews onboarding applications for any kind of missing or inconsistent information
- Extracts and verifies relevant details from customer and business documents
- Runs approved KYC, sanctions, PEP, and AML checks across connected systems
- Investigates if there are any potential matches and collects supporting information for analysis
- Reroutes high-risk cases to compliance teams for manual review
4. Loan Origination and Underwriting
Loan processing is more than just calculating a credit score. Your teams might need to review bank statements, income statements, existing liabilities, credit history, and lending policies before approving any application. Manually getting all of this in one frame can delay decisions and increase underwriting workloads.
What does an Agentic AI system do differently:
- Reads financial statements and extracts borrower-level information
- Calculates relevant income, liability, and cash flow indicators
- Checks borrower information against lending policies
- Identifies gaps or inconsistencies that need clarification
- Creates an underwriting file with the evidence needed by the credit team
5. FP&A and Rolling Forecasts
FP&A teams need to understand not only whether revenue or costs changed but also why they changed and what it means for the next forecast. Most of this analysis still includes collecting inputs from various teams and manually updating forecast models. This makes frequent forecasting difficult.
What does an Agentic AI system do differently:
- Keeps an eye on actual performance against budgets and forecasts
- Investigates material variances down to the underlying business driver
- Collects approved inputs from finance and operating teams
- Updates rolling forecasts when any of the defined assumptions change
- Runs a what-if scenario for revenue, costs, margins, and cash flow
Need to automate FP&A and forecasting workflows?
Opt for our financial software development services, and build forecasting workflows that connect your financial data, models, and reporting in one place.
6. Regulatory Reporting
Regulatory reporting needs financial data to be collected, transformed, monitored, and submitted accordingly to specific reporting requirements. Teams mostly repeat the same preparation and validation work for every reporting cycle. Changes in reporting rules can also require manual updates to existing processes.
What does an Agentic AI system do differently:
- Identifies and collects the data needed for a specific regulatory return
- Applies predefined reporting calculations and mapping rules
- Checks figures against validation requirements before submission
- Identifies changes in reporting requirements that may affect the workflow
- Creates an evidence trail linking reported figures to their source data
7. Treasury and Cash Monitoring
Treasury teams need to know where most of the cash is held, what payments are coming due, and whether the available funds are enough to cover the upcoming needs. The challenge is that cash keeps moving constantly across accounts, entities, currencies, and payment channels. A static daily report can miss important changes between reporting cycles.
What does an Agentic AI system do differently:
- Continuously watches account balances and expected cash movements
- Compares available liquidity with upcoming obligations
- Detects unexpected changes in cash inflows and outflows
- Identifies accounts or entities approaching any liquidity thresholds
- Helps the treasury teams evaluate funding or cash-position actions against approved policies
8. Dispute Resolution
Payment disputes need more than just checking whether the transaction happened. Teams may need to review the payment details, customer communications, merchant evidence, delivery information, and previous disputes. Agentic AI in finance can bring this information together, review the case, and help prepare the right evidence, reducing the time needed to resolve disputes.
What does an Agentic AI system do differently:
- Builds a complete dispute timeline from the available information
- Determines which kind of evidence is required for the specific dispute
- Requests or retrieves missing evidence through approved workflows
- Compares the case against relevant dispute rules and previous cases
- Prepares the evidence package for the person making the final decision
9. Credit Risk Scoring
A credit risk score gives lenders a risk signal, but does not always explain what is changing underneath it. Borrower risk can shift because of rising utilization, missed payments, declining cash flows, or any changes in financial behavior. Manually monitoring all of these key changes across such a large portfolio is impossible.
What does an Agentic AI system do differently:
- Monitors borrower behavior between scheduled credit reviews
- Detects changes in repayment, utilization, income, and financial health indicators
- Explains which factors are driving a change in risk
- Triggers predefined review workflows when risk crosses a threshold
- Creates updated borrower risk summaries for the credit teams
10. Collections and Portfolio Monitoring
Collections teams cannot treat every overdue account in the same way. A customer who might have missed one payment needs to have a different approach from a borrower who might show a long-term deterioration in repayment behavior. Agentic AI in finance can spot these patterns early and help teams choose the right action for each customer.
What does an Agentic AI system do differently:
- Identifies early changes in repayment behavior before serious delinquency
- Segments accounts based on likely collection needs and portfolio risk
- Determines the next approved collection action for each segment
- Adjusts the follow-up timing based on customer responses and payment activity
- Escalates accounts showing worsening risk or requiring human intervention
Together, these agentic AI use cases in finance show how AI agents can reduce manual work, handle routine tasks, spot issues early, and help finance teams make faster decisions.
Ready to put AI agents to work in your finance workflows?
Build smarter, safer solutions with our AI agent development services tailored to your finance needs.
What New Rules Mean for Your Pilot in 2026
As of now, there is no separate U.S. federal rulebook for Agentic AI in finance; instead, banks still have to apply existing requirements around model risk, data, consumer protection, operational resilience, and human oversight.
Thus, in 2026, your pilot should be designed around the risk of the workflow, not the capability of the AI.
The Fed's New Guidance Skips Agentic AI, So the Risk Is Still Yours
As of April 2026, the Federal Reserve, OCC, and FDIC issued revised model risk management guidance. This update specifies that generative AI and agentic AI are outside the scope of that specific guidance.
This does not mean that banks can easily deploy autonomous agents without controls. The Fed says the banks should use their existing risk management frameworks and add controls based on the risks of each AI application.
For the 2026 pilot, this means:
- Start with low-risk workflows such as reconciliation, alert enrichment, or internal reporting before giving any agent authority over payments, credit decisions, or customer outcomes.
- Define what the agent can change, make sure to limit the systems it can access, and specify which actions need to be approved.
- Always keep an audit trail; make sure to record the data used, actions taken, decisions made, and human overrides.
- Keep compulsory human reviews when an action could create financial, regulatory, or customer harm.
- Check what happens when data is missing, a system is unavailable, or the agent makes the wrong decision.
The rule is simple: the Fed may not have separate “Agentic AI” rules, but the bank is responsible for the outcome.
The EU AI Act's High-Risk Rules Are Being Phased In
The EU AI Act does not mean every finance system is high-risk. The key question here is what agent is being used and what decisions it can influence. For agentic AI in finance, the risk level depends on the specific use case.
For example, AI used to assess a person’s creditworthiness can fall under the high-risk category, while fraud detection is treated differently under the Act.
There is also an important update: the high-risk rules for standalone systems have been pushed to December 2, 2027, giving financial institutions more time to prepare. The delay does not remove the requirements.
For an agentic AI pilot check:
- Whether the agent can affect credit, access to financial services, or other high-impact decisions.
- Keep human oversight involved where an agent can materially affect customers.
- Test accuracy, bias, cybersecurity, and failure cases before deployment.
- Keep a record of how the system works, what data it uses, and how decisions are being monitored.
- Build all of the above controls into the pilot now rather than waiting for the 2027 deadline.
A 90 Day Plan to Test Your First Use Case
Your first agentic AI in finance pilot should prove value without creating unnecessary risk. Always make sure to use the first 90 days to move from a controlled workflow to limited autonomy, rather than trying to automate the entire process at once.
Weeks 1 to 4: Pick the Use Case and Check Your Data
Make sure to choose a single workflow with a clear starting point, repeatable steps, and measurable output. Check whether the agent can access the required data and systems and define what it can and cannot do.
Weeks 5 to 8: Run It Alongside Humans First
Allow the agent to perform the workflow while your team makes the actual decisions. Compare all of its actions with human results and track accuracy, exceptions, time saved, and unnecessary actions.
Weeks 9 to 12: Let It Run on Its Own, With Checks
Give the agent limited autonomy only after it meets your pilot targets. Keep all of the approval gates for high-risk actions, log every step, and set clear rules for when a workflow must return to a human.
A 90-day pilot helps you test agentic AI use cases in finance safely, measure the results, and slowly move from human-led work to limited AI autonomy.
Match AI Agents in Finance to the Right Pilot Scope
For agentic AI in finance, the right pilot scope depends on the risk and complexity of the workflow. Use these three tiers to decide how much freedom to give the agent.
| Use Case Tier
| Best Fit | Example Use Cases | What You Need | 90-Day Goal |
|---|
| Tier 1: Low Risk | Simple repeatable tasks | Dispute or collections follow-up | Clear data and one main system | Prove time savings and accuracy |
| Tier 2: Medium Risk | Workflow across multiple systems | Reconciliation, KYC/onboarding
| Connected data and clear rules for exceptions | Prove that the agent can work reliably |
| Tier 3: High-Risk | Decisions with customer and regulatory impact | Credit risk scoring, regulatory reporting | Strong controls and human oversight | Test the workflow before giving the agent more autonomy
|
Always start with tier 1 and move to more complex and higher-risk workflows once the agent performs reliably.
How Bacancy Technology Evaluates Agentic AI in Finance Use Cases Before Deployment
Not every finance workflow is ready for an autonomous agent. As part of financial services digital transformation, at Bacancy Technology, we carefully look at the workflow, data, risk, and controls first to make sure that the use case can deliver value without adding unnecessary risk. How we help you:
- Start With the Workflow, Not the Model
We first map out how the work is done today, including the decisions made, systems, exceptions, and approval steps. This process helps us find where an agent can remove real manual work instead of adding AI where simple automation would be enough.
- Test Against Real Financial Data Before Scaling
We do not rely on sample or demo data to judge an agent. We test it against real financial data, historical cases, exceptions, and incomplete records to see how it performs under operating conditions.
- Build Guardrails Around Risk Tier, Not After Launch
We always ensure we match the level of autonomy to the risk of the workflow. A reconciliation agent may need fewer controls than an agent involved in credit decisions or regulatory reporting. We define access limits, approval points, escalation rules, and audit logs before deployment.
- Monitor and Revalidate Post-Deployment
We continue to monitor the agent once it goes live. We always check for accuracy, exceptions, actions, and business outcomes, then revalidate the workflow when financial data, customer behavior, fraud patterns, or regulations change.
Common Mistakes When Prioritizing Agentic AI in Finance
1. Do not start with credit decisions or autonomous payments. Always begin with a workflow where mistakes are easier to detect and contain.
2. If any financial data is incomplete or outdated, or spread across disconnected systems, the agent will struggle to work reliably.
3. Agentic AI will not fix unclear processes. First, you need to simplify the workflow, remove unnecessary steps, and then need to decide what the agent should handle.
4. Start with limited access and human approval for high-impact actions. Increase autonomy only after the agent proves to be reliable.
5. Do not expand a pilot simply because the technology works. Scale only when it shows measurable gains in accuracy, processing time, cost, or employee productivity.
Conclusion
Agentic AI in finance can improve finance workflows, but the starting points matter. Make sure to always begin with a clear, repeatable use case where data is ready, and risks are manageable. Test it with humans, measure real results, and add controls before increasing autonomy. You can also partner with the right Financial IT services and solutions provider to build, test, and scale the right use case without taking on everything in-house. The goal is not more AI, but faster, safer, and more reliable finance operations.
Frequently Asked Questions (FAQs)
There is no standard price. Cost depends on the workflow, number of systems involved, data access, and how much autonomy you give the agent. A focused pilot around one workflow is usually a better starting point than building an enterprise-wide AI platform.
The agent should not have unlimited authority from day one. We set approval points based on the risk of the workflow. For example, an agent may handle a low-risk reconciliation exception automatically, while credit decisions, payment actions, or high-impact fraud cases may require human approval.
Yes. Most pilots are built around the systems already in place, such as core banking, ERP, CRM, payment, and fraud platforms. APIs and middleware allow the agent to read data and take approved actions without replacing the underlying systems.
Start with a task that happens often, has clear steps, enough data, and a clear result. Reconciliation, fraud alerts, and back-office tasks are good first pilots. High-risk tasks like lending or credit approval should come later.